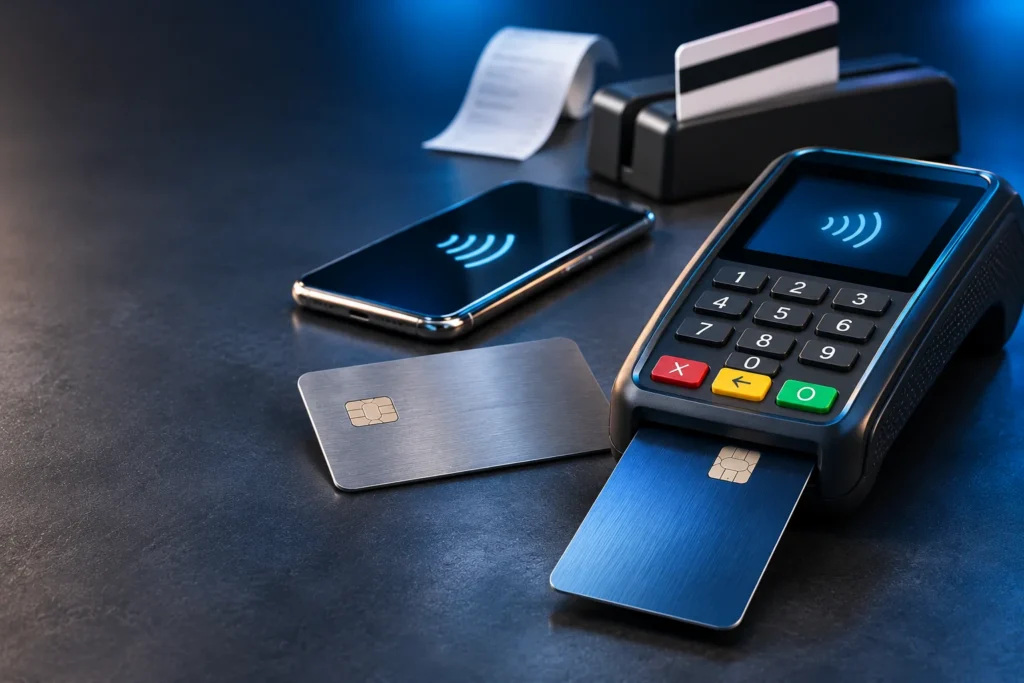
Chip-and-PIN vs. chip-and-signature is a comparison of how cardholders verify an EMV chip payment. Both methods use chip technology, but one uses a personal identification number (PIN) while the other uses a signature when that verification method is required.
However, those are not the only ways to pay. Modern cards and payment terminals can also support transactions without a PIN or signature, magnetic-stripe payments, contactless cards, mobile wallets, and online authentication.
The important distinction for business owners is that the technology used to read a card is not the same thing as the method used to verify the cardholder. Confusing those two concepts can lead to incorrect assumptions about payment security, fraud liability, and the equipment a business actually needs.
I’ve worked in merchant services since co-founding Valued Merchant Services in 2006. During that time, I’ve seen businesses move from magnetic-stripe terminals to EMV chips and contactless payment systems. Yet one question keeps coming up: why does one transaction ask for a PIN, another request a signature, and a third require nothing at all?
This guide explains those differences and what they mean for merchants.
Chip-and-PIN vs. Chip-and-Signature: What’s the Difference?
Chip-and-PIN and chip-and-signature both involve an EMV chip card interacting with a compatible payment terminal.
The difference is the cardholder verification method, often abbreviated as CVM.
Quick Answer
Chip-and-PIN uses an EMV chip transaction with PIN verification. Chip-and-signature uses an EMV chip transaction with a signature when required. Both benefit from chip-based transaction authentication, which helps resist certain counterfeit-card attacks. A PIN can provide stronger verification that the person presenting the card knows the required secret, but neither method prevents every type of fraud. Many modern EMV transactions require neither PIN nor signature.
EMVCo, the organization responsible for maintaining EMV specifications, confirms that EMV payments support online PIN, offline PIN, signature, no CVM, and consumer-device verification methods. Read EMVCo’s explanation of cardholder verification methods.
In This Guide
- Nine payment and verification methods compared
- How chip-and-PIN works
- How chip-and-signature works
- Chip cards without PIN or signature
- Traditional magnetic-stripe signatures
- Contactless cards and mobile wallets
- Manual entry and online verification
- Which payment method is more secure?
- What merchants should do
- Frequently asked questions
First, Separate Card Authentication From Cardholder Verification
Before comparing the payment methods, two concepts need to be clear.
Card Authentication: Is the Payment Credential Genuine?
An EMV chip transaction uses cryptographic information, including transaction-specific data, to help authenticate a genuine payment credential.
Unlike a conventional magnetic stripe, which relies on comparatively static recorded information, EMV technology can generate a dynamic cryptogram for a transaction.
This makes certain forms of counterfeit-card fraud more difficult.
However, authenticating the payment credential does not automatically establish that the person presenting it is authorized to use it.
Cardholder Verification: Is the Person Authorized to Use It?
Cardholder verification is a separate process.
Depending on the card, terminal, network rules, transaction type, and applicable requirements, verification may involve entering a PIN, signing, using a device-based method, or proceeding without an additional CVM.
A PIN may be verified online by the issuer or offline by the chip. A smartphone may use biometric or passcode verification. Some transactions require no additional cardholder verification.
The merchant should follow the payment terminal’s supported prompts rather than choose a verification method based only on personal preference.
Source: EMVCo: Contact Chip Technology.
Nine Card Payment and Verification Methods Compared
These methods are not all directly interchangeable. Some describe how payment information is captured; others describe how the customer is verified.
| Method | Customer action | EMV chip authentication? | Important distinction |
|---|---|---|---|
| 1. Chip-and-PIN | Insert card and enter PIN | Yes | PIN verifies the cardholder under the supported process |
| 2. Chip-and-signature | Insert card; sign if prompted | Yes | Signature is separate from chip security |
| 3. Chip with no CVM | Insert card; no additional verification prompt | Yes | No PIN does not mean no chip security |
| 4. Magnetic stripe and signature | Swipe; sign if applicable | No | Traditional stripe data lacks EMV chip authentication |
| 5. Magnetic stripe and PIN | Swipe and enter PIN | No | PIN verification does not make a stripe transaction an EMV transaction |
| 6. Contactless card | Tap a compatible physical card | Yes, for EMV contactless | PIN, no CVM, or another supported process may apply |
| 7. Mobile wallet | Tap phone or wearable | Can use EMV contactless | Device authentication may serve as the CVM |
| 8. Manual card entry | Card details entered into an approved interface | No chip authentication from key entry | Different fraud controls and handling rules apply |
| 9. Online payment | Card or wallet checkout; possible authentication challenge | Not a physical chip read | May use EMV 3-D Secure or other remote authentication tools |
Important: This comparison describes common implementations. The exact customer experience depends on the card, issuer, network, terminal configuration, payment application, and jurisdiction.
1. How Chip-and-PIN Payments Work
In a typical chip-and-PIN transaction, a customer inserts an EMV chip card into a compatible reader and enters a personal identification number when prompted.
The chip transaction supplies cryptographic data, while the PIN performs a separate cardholder verification function.
Online PIN vs. Offline PIN
There are two important ways a chip transaction may verify a PIN.
Online PIN: The terminal securely captures the PIN and sends the protected PIN information through the appropriate payment infrastructure for verification by the issuer or its designated systems.
Offline PIN: The chip card performs PIN verification locally as part of the supported EMV process.
These methods differ technically, even though the customer may experience both as entering a PIN into the terminal.
Not every card, terminal, or transaction environment supports both.
Does Every Chip-and-PIN Transaction Involve a Debit Card?
No. PIN verification is commonly associated with debit transactions in the United States, but chip-and-PIN is not synonymous with debit.
Some credit cards also support PIN verification, particularly in international markets and certain unattended payment environments.
Likewise, some debit-card purchases can be completed without a PIN, depending on the transaction and applicable network rules.
Advantages of Chip-and-PIN
- The EMV chip helps resist certain counterfeit-card attacks.
- PIN verification adds a cardholder verification step when properly supported.
- PIN-based transactions can be useful at compatible unattended terminals.
- Merchants follow a terminal-driven verification process rather than judging a handwritten signature.
Limitations of Chip-and-PIN
PIN verification does not prevent every form of fraud. Criminals may exploit compromised accounts, stolen PINs, merchant-system vulnerabilities, or online payment channels that do not require the physical chip.
Additionally, requiring a PIN for every purchase is not always possible or appropriate. The accepted method depends on supported payment rules and capabilities.
Merchant takeaway: Support legitimate terminal PIN prompts and train staff not to request that customers say their PIN aloud or disclose it to employees.
2. How Chip-and-Signature Payments Work
Chip-and-signature uses the same broad category of EMV contact-chip technology as chip-and-PIN, but the customer may be asked to sign instead of entering a PIN.
The signature is the selected cardholder verification method. It is not the source of the chip’s cryptographic protection.
Is Chip-and-Signature Still Used?
Yes, signature remains a recognized method in some transaction environments, but signatures became optional for many in-person U.S. and Canadian card purchases beginning in April 2018.
Visa removed its general signature requirement for EMV-enabled merchants in those markets, and Mastercard announced that merchants could stop collecting signatures for in-store credit and debit purchases.
That means it is outdated to describe a handwritten signature as an unavoidable part of modern credit card acceptance.
Sources: Visa: Contactless Payment Guidance and Mastercard: Retiring Customer Signatures.
Is Chip-and-Signature Less Secure Than Chip-and-PIN?
For verifying that the person presenting a card knows a required secret, properly implemented PIN verification generally provides a stronger check than an unchecked or easily imitated handwritten signature.
However, that is not the same as saying a chip-and-signature transaction lacks EMV security.
Both can use the chip’s dynamic authentication mechanisms. Furthermore, transaction risk depends on other controls, including issuer authorization, payment-network monitoring, device security, and the circumstances of the transaction.
Therefore, assigning a universal fraud rate or guarantee to either method would be misleading.
Merchant takeaway: If the terminal requests a signature, follow the current procedures supplied by your acquirer and applicable network. Do not add unnecessary signature steps to transactions where they are not required.
3. EMV Chip Transactions With No PIN or Signature
One of the most misunderstood methods is no CVM, meaning no additional cardholder verification method is required for that particular transaction.
A customer may insert a chip card and complete a purchase without entering a PIN or signing.
That is not automatically a sign that the transaction was processed insecurely.
Why Would a Chip Transaction Require No CVM?
Payment systems can use different verification rules based on the card, terminal capabilities, transaction conditions, risk considerations, and applicable network or market requirements.
No-CVM transactions may be appropriate under those rules.
Although the customer is not asked to enter a PIN or sign, the EMV chip can still participate in card authentication.
Does No CVM Mean No Security?
No. It means the transaction did not require an additional customer verification step under the selected method.
Other controls, such as chip cryptography, issuer authorization, risk monitoring, and terminal security, may still be active.
Merchant takeaway: A legitimate no-CVM transaction should not be treated as defective simply because the terminal skips a signature or PIN prompt.
4. Traditional Magnetic-Stripe Cards and Signatures
Traditional magnetic-stripe payments use information recorded on the stripe of a card.
Historically, merchants often asked customers to sign receipts as part of the cardholder verification process.
However, a magnetic stripe and a signature are not equivalent to an EMV chip transaction.
Why Magnetic Stripes Have Different Security Limitations
Traditional magnetic-stripe data is largely static. If criminals obtain usable stripe information, they may attempt to create a counterfeit card or otherwise misuse that information.
By contrast, EMV chip payments incorporate transaction-specific cryptographic elements that make simple copying of payment credentials less useful for certain in-person counterfeit attacks.
This is a major reason payment technology shifted toward EMV.
Does Signing a Receipt Make a Magnetic-Stripe Payment Secure?
A signature may have served as a verification step under historical procedures, but it does not change the underlying properties of magnetic-stripe data.
Furthermore, many in-person signature requirements were removed in 2018.
The merchant should not assume that collecting a signature eliminates fraud risk or changes every applicable liability rule.
What About Chip Cards That Still Have a Stripe?
Some chip cards also have a magnetic stripe for compatibility with supported payment environments.
However, a merchant should not swipe a functioning chip card simply to avoid the chip process.
Where permitted, fallback procedures are governed by payment-network and processor requirements. Fallback should not be improvised by staff.
Merchant takeaway: Use the payment interface indicated by a properly functioning, configured terminal, and investigate repeated requests to fall back from chip to magnetic stripe.
5. Magnetic-Stripe Payments With PIN Verification
Not every PIN transaction uses an EMV chip.
Traditional magnetic-stripe debit transactions can also involve online PIN verification.
For example, a compatible debit transaction may use stripe data for card reading and a protected PIN-entry process for cardholder verification.
That does not provide the same chip-based authentication as an EMV transaction.
This distinction is important when a merchant hears the phrase “PIN debit.” It describes aspects of a debit transaction, not necessarily the card-reading technology.
Merchant takeaway: Evaluate the complete transaction type rather than assuming a PIN automatically means EMV technology was used.
6. Contactless EMV Cards: Tap Without Inserting
A compatible contactless payment card uses near-field communication, or NFC, to interact with a supported terminal when the customer taps or holds the card nearby.
Modern EMV contactless transactions use cryptographic mechanisms that generate transaction-specific security data.
Therefore, a proper EMV tap is not simply a magnetic-stripe swipe without physical contact.
Do Contactless Cards Require a PIN?
Sometimes, but not always.
Depending on the card, country, transaction, terminal, and payment-network requirements, a contactless card transaction may proceed without an additional CVM or may require verification.
The terminal may direct the customer to enter a PIN or use another supported process.
Merchants should not impose their own universal contactless PIN threshold. Actual rules and customer prompts depend on the relevant payment environment.
Is a Contactless Card More Secure Than Chip-and-PIN?
There is no universal answer because these descriptions compare different characteristics.
Contactless EMV describes the way payment data is exchanged and authenticated. Chip-and-PIN describes a contact-chip transaction with a particular cardholder verification method.
Both can include valuable security controls, and neither is fraud-proof.
Source: EMVCo: Contactless Chip Specifications.
For a separate guide to accepting contactless payments, see Contactless Payments for Small Business.
7. Mobile Wallets: Biometric and Device-Based Verification
Customers may use compatible smartphones or wearable devices to make contactless payments through supported digital wallets.
Many mobile wallets use device-based authentication, such as a fingerprint, facial recognition, passcode, or another approved method.
EMV terminology refers to supported consumer-device cardholder verification as CDCVM.
What Is CDCVM?
Consumer Device Cardholder Verification Method allows a supported device to verify the user through its own authentication capabilities.
For example, a payment may involve the customer’s phone verifying their identity through an available biometric or passcode process.
This differs from entering a card PIN into the merchant’s payment terminal.
Do Mobile Wallets Use the Actual Card Number?
Many mobile wallets use network tokenization or other payment credentials designed to reduce unnecessary exposure of the underlying card number.
However, the details depend on the wallet, network, issuer, and implementation.
A digital wallet should not be described as universally immune to fraud or account takeover.
Why This Matters for Merchants
A terminal can complete an eligible mobile wallet payment without asking the customer to enter a separate terminal PIN or provide a signature.
That does not necessarily mean the customer was never authenticated. Verification may have occurred on the device.
Merchant takeaway: Confirm that your payment equipment and software support the relevant contactless wallets, and follow the prompts rather than requesting additional information that the transaction does not require.
8. Manually Keyed Card Transactions
Some businesses accept payments by entering card details into an approved terminal, virtual terminal, or other payment interface.
This can occur in certain telephone orders, supported business-service workflows, or permitted fallback situations.
Manual entry does not read or authenticate a physical EMV chip.
Why Is Manual Entry Different?
Even when the customer provides valid card information, the merchant does not obtain the same chip-authentication evidence that would come from a properly performed chip transaction.
Manual-entry transactions may therefore require different fraud controls, have different pricing, and carry different dispute or liability considerations.
Businesses should also avoid collecting payment details through unapproved email, text messages, notes, or insecure documents.
Merchant takeaway: Use approved payment tools for manual entry and follow your processor’s specific procedures. Do not substitute keyed entry for an ordinary chip transaction simply for convenience.
9. Online Card Payments and EMV 3-D Secure
Online purchases typically do not involve physically inserting or tapping the customer’s card into a merchant-controlled terminal.
Consequently, the traditional chip-and-PIN versus chip-and-signature comparison does not directly describe ecommerce verification.
Online merchants use different fraud-prevention and authentication tools.
What Is EMV 3-D Secure?
EMV 3-D Secure (EMV 3DS) is a protocol that enables participating merchants and card issuers to exchange transaction and device information to help authenticate card-not-present payments.
Some transactions may complete without an additional customer challenge. Others may require a one-time passcode, biometric verification, or another supported authentication step.
The precise experience depends on the issuer, checkout integration, transaction risk, and other requirements.
What About CVV and Address Verification?
CVV and Address Verification Service (AVS) may also be used in eligible payment environments.
However, they serve different purposes from EMV chip authentication or EMV 3DS.
CVV checks card security-code information. AVS compares supported billing-address data. Neither should be presented as proof that the individual placing the order is legitimate.
Similarly, an authorization approval does not guarantee that a transaction cannot later be disputed.
Source: EMVCo: EMV 3-D Secure.
Merchant takeaway: Use a layered ecommerce fraud strategy suited to your sales channels and work with your gateway or processing provider to determine which authentication tools are supported.
Which Is More Secure: Chip-and-PIN, Chip-and-Signature, Swipe, or Tap?
Security depends on which risk you are trying to address.
A meaningful comparison separates counterfeit-card resistance, cardholder verification, and protection of payment data within merchant systems.
Counterfeit-Card Protection
Proper EMV contact and contactless transactions provide stronger protection against certain traditional counterfeit-card attacks than conventional magnetic-stripe transactions.
This advantage comes primarily from the chip-based authentication mechanisms, not from whether the customer signs a receipt.
Verification of a Person Using a Card
A properly implemented PIN can help verify that the person presenting the card knows the required secret.
Signature verification generally offers a different, often weaker check.
Device-based methods can also provide meaningful authentication, depending on their implementation and the surrounding transaction controls.
Meanwhile, an eligible no-CVM transaction can still involve issuer authorization and chip authentication.
Protection Against Ecommerce Fraud
A physical EMV chip does not independently prevent fraud in a transaction where the chip is not presented.
Online payments require appropriate card-not-present controls, which may include EMV 3DS and other gateway or issuer fraud-management tools.
Protection Against a Data Breach
Chip technology is not a substitute for securing payment systems.
Businesses still need appropriate payment-device security, PCI DSS controls, access management, software maintenance, and vendor oversight.
Validated point-to-point encryption and tokenization can provide additional protections when properly implemented.
However, neither should be treated as a guarantee against every breach or a substitute for other applicable requirements.
The PCI Security Standards Council explains that validated P2PE solutions encrypt payment data from the point of capture to a secure decryption environment and can simplify certain compliance responsibilities.
For a broader discussion, read our Secure Credit Card Processing: 10 Steps for Merchants guide.
How Tokenization and Encryption Fit Into These Methods
The original VMS articles discussed tokenization and point-to-point encryption as though they were alternative types of chip-card verification.
They are not.
Encryption protects data by transforming it using cryptographic methods so that unauthorized parties cannot readily read it.
Tokenization substitutes an appropriate token for sensitive payment credentials in a supported system.
Depending on the implementation, tokens can reduce how widely original payment credentials are exposed.
These technologies can work alongside chip-based payments, mobile wallets, and other processing tools.
However, their purposes differ from verifying a cardholder with a PIN, signature, or device.
For example, a merchant might use a compatible EMV terminal with a validated P2PE solution, while another system uses tokens for stored customer payment credentials.
The merchant’s actual security and compliance obligations depend on the complete environment, not simply on whether the provider advertises encryption or tokenization.
Are Signatures Still Required for Credit Card Purchases?
Not generally for every in-person purchase in the United States.
During April 2018, major payment-network changes made signatures optional for many transactions, including Visa EMV-enabled merchants in the United States and Canada and Mastercard in-store purchases in those markets.
That development reflected a shift toward chip authentication, improved risk systems, digital credentials, and other verification processes.
However, it would be inaccurate to claim that signatures have been prohibited everywhere or eliminated from every payment arrangement.
Businesses must still follow current network, acquirer, and transaction-specific requirements.
Merchant takeaway: Do not require customers to sign every card receipt merely because your business used that procedure years ago. Verify whether your current setup actually requires it.
Does Chip-and-PIN Reduce Fraud Liability for Merchants?
No single verification method guarantees that a merchant will avoid chargebacks or fraud liability.
Payment-network liability rules can depend on the type of fraud, supported technology, how the transaction was processed, authentication results, and other circumstances.
For example, the U.S. EMV liability shift that began in October 2015 addressed certain counterfeit-card transactions, with exceptions and separate implementation schedules.
It did not mean that merchants automatically became responsible for every disputed payment unless a PIN was entered.
Nor does it mean that a transaction with a PIN is exempt from future disputes.
Practical advice: Ask your acquirer or processor which rules apply to your equipment, transaction categories, and acceptance channels. Avoid relying on broad statements about who always pays for fraud.
What Small Business Owners Should Do With Their Payment Equipment
Most merchants do not need to choose a single verification method and force every customer to use it.
Instead, they need suitable equipment, proper configuration, trained employees, and clear processing procedures.
1. Confirm That Your Terminal Supports the Payment Methods You Need
Check whether your equipment supports EMV contact-chip transactions, eligible contactless cards, relevant mobile wallets, and PIN entry when required.
Availability depends on device hardware, payment software, processor configuration, and other factors.
2. Follow the Terminal’s Instructions
If the terminal requests a PIN, direct the customer to enter it privately.
If it asks for a signature, follow the appropriate supported procedure.
If no CVM is required, do not create an unnecessary authentication step based on an outdated assumption.
3. Do Not Bypass Chip Reading to Speed Up Checkout
Repeatedly swiping chip cards or keying card details instead of using the chip interface can create operational and fraud-management concerns.
If a terminal repeatedly fails to read a valid chip, investigate the device or contact your processor.
4. Train Employees on Contactless and Mobile Wallet Payments
Employees should understand that a phone or watch may authenticate the customer on the device.
Consequently, they should not assume that a transaction lacks verification simply because no PIN or signature appears on the merchant terminal.
5. Review Your Ecommerce Security Separately
A secure in-store chip terminal does not automatically protect the business’s online checkout.
Evaluate gateway features, eligible EMV 3DS support, fraud controls, and PCI DSS responsibilities for each payment channel.
6. Understand Your Actual Processing Costs
Different card products, transaction types, and processing arrangements can have different fees.
However, no reliable universal rule says chip-and-PIN is always the cheapest method or that every signature transaction costs more.
To understand what your business is paying, review your actual statements and the terms of your merchant agreement.
Our seven-step guide to reading a credit card processing statement explains that process.
7. Review Security and Service Before Replacing Equipment
Before upgrading, determine whether your existing payment setup already supports the required technologies and meets your operational needs.
A compatible software update or configuration change may sometimes address an issue, while other situations require different hardware.
For a more detailed evaluation of payment hardware and business workflows, see our guide to choosing a credit card processor.
Examples: Which Card Verification Method Might a Merchant Encounter?
The following examples are illustrative. They are not promises that a particular network, bank, or terminal will always behave the same way.
Example A: Retail Store With a Chip-and-PIN Prompt
A customer inserts an eligible chip card into a configured terminal. The terminal asks for a PIN.
The customer enters the PIN privately, and the transaction proceeds through the supported verification and authorization processes.
The clerk should not ask the customer to disclose the PIN or attempt to override the prompt without approved instructions.
Example B: Restaurant Customer Using a Chip Card Without a Signature
A customer inserts a compatible EMV chip card. The terminal completes the transaction without requesting a signature.
That does not automatically mean the merchant skipped EMV security. The card’s chip authentication and other supported controls may still be used.
Example C: Customer Tapping a Smartphone
A customer authenticates on a compatible phone and taps it at a contactless terminal.
The terminal may receive the supported payment and cardholder verification information without requiring a separate terminal PIN.
The precise behavior depends on the wallet, terminal, and transaction requirements.
Example D: A Business Taking Payment by Telephone
A customer provides payment details for an eligible telephone order. The business enters them using an approved virtual terminal.
That transaction does not read the physical EMV chip. The business therefore needs to follow appropriate card-not-present procedures and avoid storing sensitive details in unapproved systems.
Frequently Asked Questions About Chip-and-PIN, Signatures, and Other Card Methods
What is the main difference between chip-and-PIN and chip-and-signature?
Both use EMV chip technology, but chip-and-PIN involves PIN verification while chip-and-signature uses a signature when required. The chip’s transaction authentication is separate from the customer’s verification method.
Is chip-and-PIN more secure than chip-and-signature?
PIN verification generally provides a stronger check that the person using the card knows the required secret than an ordinary signature. However, both methods can use EMV chip authentication, and neither prevents all fraud.
Is a chip card the same thing as a chip-and-PIN card?
No. EMV chip cards can support different cardholder verification methods, including online PIN, offline PIN, signature, and no CVM. A chip card does not necessarily require a PIN for every purchase.
Why does my credit card sometimes require no PIN or signature?
The card and payment system may select a no-CVM transaction under the applicable rules. Other security processes, including EMV chip authentication and issuer authorization, may still apply.
Are signatures still required on credit card receipts?
Signatures became optional for many U.S. in-person card transactions beginning in 2018. However, merchants should follow the current procedures applicable to their payment setup and transaction types.
What is the difference between a traditional signature card and a chip-and-signature card?
A traditional signature card transaction may rely on magnetic-stripe data and a signature. A chip-and-signature transaction uses EMV chip authentication and may request a signature as its separate cardholder verification step.
Does a PIN make a magnetic-stripe transaction an EMV transaction?
No. A magnetic-stripe debit transaction can use PIN verification without obtaining the dynamic authentication information associated with a properly performed EMV chip transaction.
Do contactless cards require PIN verification?
Some transactions require a PIN or another supported verification method, while others proceed without an additional CVM. The requirements depend on the card, network, transaction, terminal, and market.
Is a mobile wallet PIN the same as a card PIN?
Not necessarily. A mobile wallet may use device-based authentication, such as a passcode or biometrics, under a supported consumer-device cardholder verification method. That is different from a terminal-entered card PIN.
What are online PIN and offline PIN?
Online PIN is verified through the appropriate issuer-connected payment infrastructure. Offline PIN is verified by the chip card itself under a supported EMV process.
Does chip-and-PIN prevent chargebacks?
No. Chip-and-PIN can support security and verification, but disputes and liability depend on several factors. No payment method eliminates all fraud or chargeback exposure.
What is EMV 3-D Secure?
EMV 3DS is an authentication protocol for eligible online and other card-not-present transactions. It allows participating merchants and issuers to exchange information and, where appropriate, request additional customer authentication.
Are tokenization and encryption cardholder verification methods?
No. Tokenization and encryption are technologies for protecting payment credentials and data. They may complement PIN, signature, no-CVM, and other payment methods, but they serve different functions.
Should a merchant force every customer to enter a PIN?
No. Merchants should use properly configured payment equipment and follow the applicable terminal and processing requirements. Not every card or transaction supports or requires PIN verification.
What should I do if an EMV chip will not read?
Follow the terminal and processor’s approved troubleshooting and fallback procedures. Do not automatically key the card number or swipe the card to bypass chip reading. Repeated problems should be investigated.
Final Thoughts: Chip, PIN, Signature, and Tap Are Not Interchangeable
Comparing chip-and-PIN vs. chip-and-signature is a useful starting point, but modern payment acceptance involves more than those two methods.
EMV chip technology helps authenticate payment credentials. A PIN, signature, device-based method, or no-CVM decision addresses a different part of the transaction. Contactless payments change how payment credentials communicate with the terminal, while ecommerce requires its own authentication and fraud-prevention approach.
For merchants, the goal should not be to force one method onto every customer.
Instead, use supported equipment, maintain appropriate security controls, train employees to follow legitimate prompts, and understand the procedures that apply to your specific payment environment.
Since co-founding Valued Merchant Services in 2006, I’ve believed that businesses deserve clear explanations of payment technology, including when their current equipment is already suitable.
The best payment setup is one that supports the customers, transactions, and business requirements you actually have.
Need Help With EMV, PIN, or Contactless Payments?
Valued Merchant Services helps businesses evaluate credit card terminals, POS systems, ecommerce payments, and processing arrangements. We can help you review whether your equipment supports the card-payment methods your customers use, explain relevant options, and identify when your existing setup may already be the right choice.
Call 800-531-8575 or email support@valuedmerchants.com. Supported verification methods, equipment features, transaction routing, pricing, and security responsibilities depend on the actual merchant arrangement. No cardholder verification method guarantees fraud prevention or immunity from disputes.
Updated November 2026. This consolidated guide replaces two VMS articles originally published in August and September 2015. Current explanations were checked against EMVCo, Visa, Mastercard, and PCI Security Standards Council resources. Technical capabilities and payment-network rules vary by environment and may change. For applicable transaction requirements, follow your acquirer’s and processor’s current documentation.
