
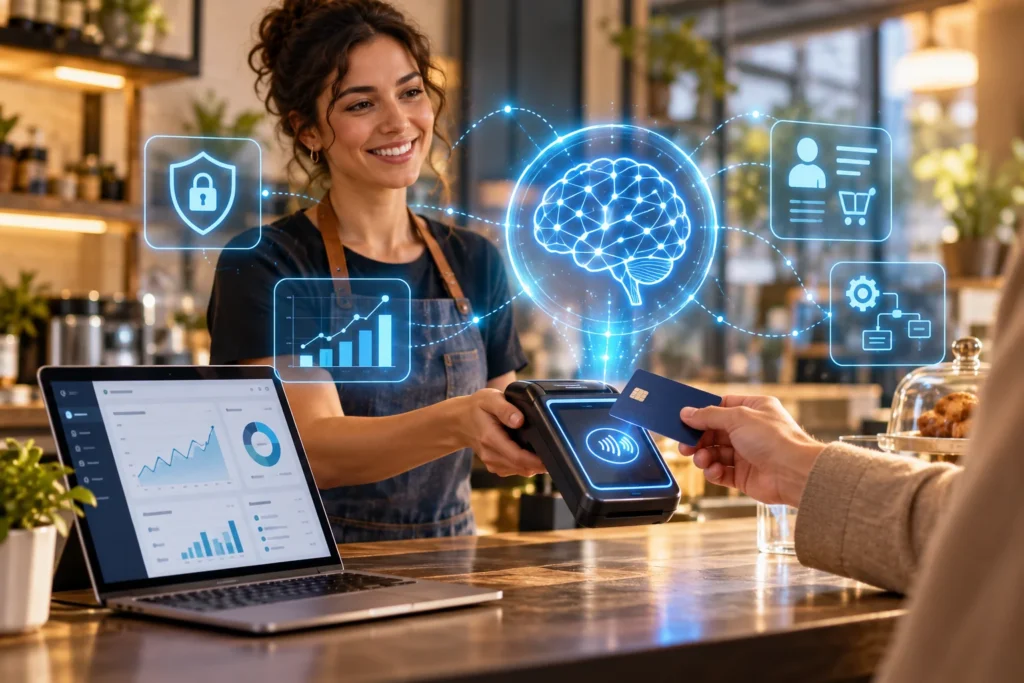
AI in payment processing is changing how businesses detect fraud, manage transactions, serve customers, and make decisions. But the important question for small business owners isn’t how advanced artificial intelligence has become. It’s whether a particular tool actually makes running their business easier, safer, or more profitable.
I’ve worked in merchant services since 2006. During that time, I’ve watched payment technology evolve from relatively simple terminals and standalone software into connected systems that handle inventory, customer information, reporting, online orders, and much more.
Artificial intelligence is another important development. Some applications are already well established, particularly in transaction monitoring and fraud detection. Others, including AI agents that can shop and initiate payments, are still developing.
For business owners, the challenge is separating useful technology from impressive marketing.
You don’t need an expensive AI platform to accept credit cards. You don’t need to replace a working POS system simply because a newer product promises intelligent features. And you shouldn’t assume that a tool labeled AI will automatically reduce fees, increase approvals, or eliminate fraud.
What you do need is a clear understanding of where these technologies fit, what they actually do, and which ones may be worth your investment.
What Is AI in Payment Processing?
Artificial intelligence in payment processing refers to software that uses techniques such as machine learning, pattern recognition, predictive analysis, or generative AI to support payment-related decisions and business operations.
These tools serve different purposes.
- Machine learning can analyze transaction patterns and estimate fraud risk based on information the system has been trained to recognize.
- Predictive analytics can help identify trends in sales, transaction activity, inventory, or customer demand.
- Generative AI can assist with customer-service responses, business reporting, product descriptions, and other language-based tasks.
- Agentic AI describes systems capable of taking actions toward a goal, potentially including finding products and initiating authorized purchases.
These aren’t interchangeable technologies, and they aren’t available in every payment platform. Some operate within a card network, bank, or payment provider’s systems without the merchant seeing them directly. Others are optional features sold alongside POS software, ecommerce platforms, or business management applications.
The distinction matters because a business owner may already benefit from AI-assisted payment security without needing to purchase an AI product at all.
How Payment Technology Evolved to Include AI
To understand where artificial intelligence fits, it helps to look at how payment acceptance has changed.
From Manual Transactions to Electronic Payments
For many years, merchants relied on manual card imprinters, paper receipts, mechanical cash registers, and time-consuming reconciliation processes.
Electronic payment terminals made authorization more efficient. Later, ecommerce gateways allowed businesses to securely transmit payment information and accept transactions through websites and other digital channels.
Chip cards, contactless payments, mobile wallets, online invoicing, and integrated POS systems continued that progression.
Each development solved particular business problems. Transactions could be processed differently, customer experiences changed, and merchants gained new tools for managing operations.
From Fixed Rules to Pattern-Based Analysis
Traditional fraud controls often depend on defined rules, such as transaction limits, address checks, or the number of payment attempts within a particular period.
Those controls remain useful. Modern risk systems can supplement them with machine learning that examines combinations of signals and detects patterns that might not fit a simple rule.
For example, one unusually large transaction isn’t necessarily fraud. But a series of payment attempts from unfamiliar devices, unusual locations, and abnormal transaction patterns may warrant additional scrutiny.
This is where AI has become particularly relevant to payment processing.
Six Ways AI Is Being Used in Payments Today
1. Fraud Detection and Transaction Risk Scoring
Fraud detection is one of the clearest current applications of AI in payment processing.
Some payment networks and fraud-management platforms evaluate transactions using information such as device characteristics, transaction velocity, purchasing history, location patterns, and other available risk signals.
They use that information to estimate whether a payment appears legitimate or suspicious. Depending on the platform and applicable rules, the result may trigger approval, additional verification, manual review, or a decline.
Visa explains how AI-based fraud detection and real-time risk scoring work within its payment security solutions.
The objective is to catch more fraudulent activity while avoiding unnecessary disruption to legitimate customers.
However, AI doesn’t make fraud prevention perfect. False positives still occur, sophisticated attacks evolve, and the results depend on the information, models, and controls used.
What merchants should ask: Does my current processor or gateway offer risk scoring? Which controls can I manage? What happens when a legitimate transaction is flagged, and how are disputed decisions reviewed?
2. Smarter Ecommerce Checkout
Checkout is another area where data-driven tools can help businesses.
Depending on the platform, intelligent checkout features may assist with recognizing returning customers, displaying appropriate payment options, identifying suspicious behavior, or determining whether additional authentication is necessary.
Some systems also use analytics to identify points in the buying process where customers abandon their carts.
But not every optimized checkout is powered by AI. Simple improvements such as accepting digital wallets, reducing unnecessary form fields, improving page speed, or making shipping costs clear can be just as important.
The measure of success should be the customer’s experience and the business’s actual results, not whether the checkout provider uses a fashionable technology label.
For businesses evaluating payment providers, our guide to choosing a credit card processor explains why compatibility, pricing, security, and support belong in the same decision.
3. Sales Forecasting and Business Reporting
A business that understands when customers buy, which products perform best, and how sales vary throughout the year can make better operational decisions.
Some AI-enabled systems can analyze historical sales data and identify recurring patterns, seasonal changes, or possible demand shifts.
For example, a restaurant may use sales information to plan staffing and inventory around busy periods. A retailer might examine product trends before placing a large order. A service business could study appointment and payment patterns to improve scheduling.
These insights can be helpful, but predictions aren’t guarantees. Unexpected weather, changing customer preferences, local events, and economic conditions can make forecasts inaccurate.
My advice is to use predictive tools to support decisions, not replace judgment.
4. Inventory and Operational Efficiency
Artificial intelligence can also complement the broader business tools connected to a POS system.
Depending on the software, features might include inventory forecasts, alerts about unusual sales patterns, purchasing recommendations, automated categorization, or reporting summaries.
These are business-management capabilities rather than credit card processing functions themselves.
That’s an important distinction when comparing products. A system can process payments reliably without offering advanced inventory intelligence, and some valuable operational features don’t require AI at all.
If you’re considering replacing equipment or software, start with our guide to choosing the right POS system. The best fit depends on your industry, integrations, reporting needs, and operating costs.
5. Customer Service and Personalized Experiences
AI tools are increasingly used to answer routine customer questions, organize support requests, help shoppers find products, and personalize recommendations.
For a merchant, these tools may reduce repetitive administrative work or help customers find answers outside normal business hours.
They also introduce responsibilities.
An AI assistant can misunderstand a refund policy, provide inaccurate information, or mishandle a conversation that should be reviewed by a person.
Businesses should decide which questions can be handled automatically, what information the system may access, and when a customer should reach a human representative.
I’ve always believed that technology should make good service easier, not become an excuse to make a business harder to reach.
6. Payment Monitoring and Reconciliation
Some financial and business software uses automated analysis to flag unusual transactions, identify possible accounting mismatches, or help categorize financial activity.
These capabilities can assist with reviewing deposits, comparing reports, detecting exceptions, or reducing repetitive data entry.
However, reconciliation still requires reliable records and accurate integrations. A software-generated summary isn’t a substitute for checking whether transactions, refunds, fees, and deposits actually match.
For many merchants, straightforward automation and dependable reporting may provide more value than a complicated AI dashboard.
What Is Agentic Commerce, and Why Does It Matter?
One of the most significant recent developments involves AI systems that can act on a shopper’s instructions.
Rather than simply recommending a product, an authorized AI agent may eventually handle more of the purchasing process, such as comparing options, selecting an item, and initiating a transaction within defined permissions.
This concept is commonly called agentic commerce.
It isn’t purely theoretical. In December 2025, Visa reported successful secure AI-initiated transactions involving its partners. In September 2026, Mastercard announced additional trust and intelligence capabilities intended to help identify and assess AI-initiated transactions.
Those developments are meaningful, but they should be viewed in context.
AI-initiated commerce is still evolving. Availability depends on the participating networks, financial institutions, technology providers, merchant integrations, and supported use cases.
A small business shouldn’t assume its existing gateway can automatically accept every form of AI-agent transaction.
What Merchants Should Watch
As these capabilities develop, merchants should pay attention to several questions:
- How does a business verify that an AI agent is authorized to act for a customer?
- How are payment credentials protected?
- What spending limits, permissions, and authentication methods apply?
- Who is responsible when an AI-initiated purchase is incorrect or disputed?
- Will existing ecommerce systems support these transactions, or will additional integration be necessary?
The future may make buying more convenient, but trust and accountability still matter.
The Security and Privacy Risks of AI in Payment Processing
AI can support payment security, but it can also introduce new risks.
That’s why I would never recommend evaluating an AI payment feature solely on convenience or potential revenue growth.
AI Doesn’t Replace PCI Compliance
Businesses that accept payment cards remain responsible for applicable payment-security requirements.
In September 2026, the PCI Security Standards Council published additional guidance addressing the deployment and security of AI systems in payment environments, including risks from malicious uses of AI.
The Council’s AI security guidance reinforces the importance of managing new technologies alongside established security controls.
A payment tool’s use of AI does not, by itself, establish that the system is PCI compliant or that a merchant has satisfied its own obligations.
Protect Customer and Payment Information
Before connecting an AI tool to business systems, determine what data it collects, where that information goes, who can access it, and how long it is retained.
Do not paste full payment card information, authentication data, or sensitive customer records into a general-purpose AI chatbot or an unapproved external tool.
Ask whether the software requires direct access to cardholder data or can operate using safer alternatives such as tokens, aggregated reports, or properly restricted information.
Security should be built into the workflow before a new tool goes live.
Watch for Errors, Bias, and Automation Risks
AI-generated recommendations can be wrong. Fraud models may inconvenience legitimate customers, forecasts may be inaccurate, and automated responses may provide misleading information.
The National Institute of Standards and Technology’s AI Risk Management Framework offers a useful reference for evaluating AI-related trustworthiness and risk.
For a small business, the practical lesson is straightforward: understand what the tool is allowed to do, monitor its results, and maintain a way for people to review consequential decisions.
What AI Features Are Actually Worth Paying For?
This is where the conversation needs to become practical.
A payment provider may promote AI-powered analytics, intelligent checkout, automated reporting, or predictive business insights. Those features can sound attractive.
But a business should compare the cost of each feature with a problem it genuinely needs to solve.
Here are the questions I’d ask before approving a new expense:
- What specific problem does this feature solve? Fraud, reporting, inventory, customer service, and checkout are different needs.
- Can the provider demonstrate the feature? Ask to see how it works using a realistic business scenario.
- What is the total cost? Include monthly software fees, processing costs, equipment, integrations, training, and cancellation terms.
- Is it compatible with what we already use? Replacing working systems can introduce avoidable expense and operational disruption.
- What information does it access? Understand the privacy, security, and compliance implications.
- Can staff review or override important decisions? Not every transaction flag, customer response, or recommendation should be accepted automatically.
- What happens when the feature fails? Ask about support, system outages, and manual alternatives.
- How will we measure the benefit? Establish a baseline for time spent, fraud losses, false declines, checkout completion, or another meaningful result.
Some merchants may find a strong business case for additional fraud tools. Others may benefit more from improved reporting or better integration between systems.
And some may discover that the payment technology they already have is doing its job.
There is nothing wrong with that outcome.
A Practical Approach for Small Businesses
Rather than investing in AI because it is becoming popular, I recommend a measured approach.
Start With Your Current Payment Setup
Review the processor, terminal, gateway, ecommerce platform, or POS software your business already uses.
Find out which features are included, which require additional subscriptions, and which are available through existing integrations.
For example, fraud monitoring may already be occurring through your payment network or processing provider even if your POS dashboard doesn’t advertise it.
Identify One Problem Worth Solving
Maybe your business spends too much time reconciling transactions. Perhaps online orders receive frequent fraud alerts, or inventory forecasting consumes hours every week.
Choose one meaningful problem and compare the available solutions.
A focused implementation is easier to evaluate than a sweeping technology change involving several new tools at once.
Test, Measure, and Keep Human Oversight
Before committing to a long-term contract, ask about demonstrations, trial periods, onboarding support, and reporting.
Compare the actual results against what you were promised.
If a tool saves time, measure that. If it reduces manual review, confirm how often it gets decisions right. If it improves checkout, look at completed purchases and customer complaints rather than relying on sales claims.
Keep employees involved, especially when customers need assistance or a system flags a legitimate transaction.
Review the Bigger Financial Picture
Payment technology should fit your overall business operations, not operate in isolation.
Our article on using payment technology to protect small-business profit margins explains why transaction costs, processing fees, labor efficiency, chargebacks, and funding speed all belong in the conversation.
Sometimes a basic operational improvement delivers a clearer return than the newest software feature.
Where Valued Merchant Services Fits In
At Valued Merchant Services, we work with businesses that have different payment needs, existing systems, budgets, and levels of technical experience.
Our role is to help merchants understand their options, whether that involves traditional card processing, merchant services, POS technology, ecommerce payments, or related business solutions.
AI-enabled features may be available through certain technology providers and integrations. Their availability, functionality, and pricing depend on the specific platform and service arrangement.
We don’t believe a merchant should change processors simply because an application has added artificial intelligence to its marketing materials.
Instead, we start by understanding the business.
What technology is already working? Where are the delays or frustrations? What are the actual processing costs? Are there opportunities to improve security, reporting, checkout, or customer service without unnecessary disruption?
Sometimes the answer is a better-integrated solution. Sometimes it’s a new tool. And sometimes the best advice is to keep what you already have.
That’s how we believe merchant services should work.
Frequently Asked Questions About AI in Payment Processing
How is artificial intelligence used in credit card processing?
AI can be used to assess transaction risk, identify unusual activity, support fraud detection, analyze payment trends, and improve some operational workflows. The specific capabilities depend on the payment network, processor, gateway, and business software involved.
Can AI prevent all payment fraud?
No. AI may improve certain fraud-detection processes, but it cannot eliminate fraud. Effective protection still depends on multiple safeguards, appropriate authentication, security controls, employee awareness, and responsible payment practices.
Do small businesses need AI-powered payment systems?
Not necessarily. Many small businesses can operate successfully with reliable payment technology that doesn’t advertise advanced AI features. The value depends on whether a particular capability addresses a real operational need at a reasonable cost.
Is AI-powered payment processing more expensive?
Not always. Some machine-learning capabilities operate within existing payment infrastructure, while optional software features may carry separate fees. Compare the complete cost of the solution and understand what is included before making a decision.
Will AI reduce credit card processing fees?
AI does not automatically lower interchange, card-network assessments, or merchant processing fees. Some related technology may improve efficiency or help manage fraud losses, but processing costs must still be evaluated using the merchant’s actual statements and program terms.
Is it safe to use AI with payment information?
Safety depends on the specific system, its security controls, data handling, and the merchant’s responsibilities. Businesses should use approved tools, protect cardholder information, follow applicable security requirements, and avoid sharing sensitive payment data with unapproved AI services.
Can customers use AI agents to make purchases?
Some technology companies and payment networks have begun implementing secure AI-initiated commerce capabilities. However, support isn’t universal. Merchant participation depends on the relevant services, integrations, authorization methods, and transaction requirements.
How can a merchant evaluate an AI payment feature?
Start with the problem the feature claims to solve. Ask about compatibility, costs, security, customer experience, human review, reporting, and support. Then measure actual results before making a larger commitment.
Final Thoughts: Smarter Payments Still Require Good Decisions
Artificial intelligence has become an important part of the broader payment technology landscape, and I expect its influence to continue growing.
But after two decades in merchant services, my perspective remains the same: business owners don’t need technology for the sake of technology.
They need solutions that work reliably, protect customer information, fit their operations, and make financial sense.
AI can help accomplish some of those goals. It can also introduce complexity if it is poorly implemented or sold without a clear understanding of the merchant’s needs.
The opportunity is real. So is the responsibility to make informed decisions.
Start with your business. Understand the problem. Review the costs and safeguards. Choose the technology that earns its place in your operation.
That’s a more dependable strategy than chasing the latest trend.
Is Your Payment Technology Working for Your Business?
Before adding new software or changing payment providers, find out whether your current processing setup is already competitive. Valued Merchant Services can review your statement, explain your actual costs, and help you understand available options.
Request a Free Processing Rate Review
No obligation to switch. For questions about payment technology or integrations, contact the VMS team or call 800-531-8575.
